What Is a Pre-Foreclosure in New Jersey? A Clear Guide
What Is a Pre-Foreclosure in New Jersey? (And Why It's Not the End)
Key takeaways
Pre-foreclosure is the early stretch — after you've fallen behind on the mortgage but before the bank completes a foreclosure and the house goes to a sheriff's sale. You still own your home.
In New Jersey, your lender generally has to send a Notice of Intention to Foreclose and wait at least 30 days before it can even file in court — so a "pre-foreclosure" letter is a warning, not a done deal.
Because NJ is a judicial-foreclosure state with one of the longest timelines in the country, pre-foreclosure usually gives you real time and real options: catch up the loan, work out a plan, or sell before the sale.
I'm not an attorney or a credit counselor — for the legal side I'll point you to the right pro, and there's free help in NJ. What I can do is give you an honest read on whether selling or structuring terms makes sense.
If you've gotten a letter with the word "foreclosure" on it, I know your stomach probably dropped. Take a breath. Over 40-plus years buying houses here in South Jersey, I've sat across from a lot of folks holding that same letter, and the first thing I tell them is usually this: pre-foreclosure is the stage where you still have the most control. It feels like the end. It's actually the window where the most doors are still open. Let me walk you through what it really means in New Jersey — plain and simple, no scare tactics.
So what does "pre-foreclosure" actually mean?
Pre-foreclosure is the period that starts when you fall behind on your mortgage and runs up until the lender completes a foreclosure — which, in New Jersey, ends at a sheriff's sale where the home is auctioned. In between those two points, you are still the owner. Your name is still on the deed. You can still live there, sell it, or work things out with the bank.
People hear "pre-foreclosure" and picture a padlock on the door next week. That's not how it works. It's a status, not an eviction. The bank is signaling that the loan is seriously past due and that foreclosure could follow if nothing changes — but "could follow" is a long way from "is happening."
How pre-foreclosure works in New Jersey
Here's the part that matters, because New Jersey does this differently than a lot of states.
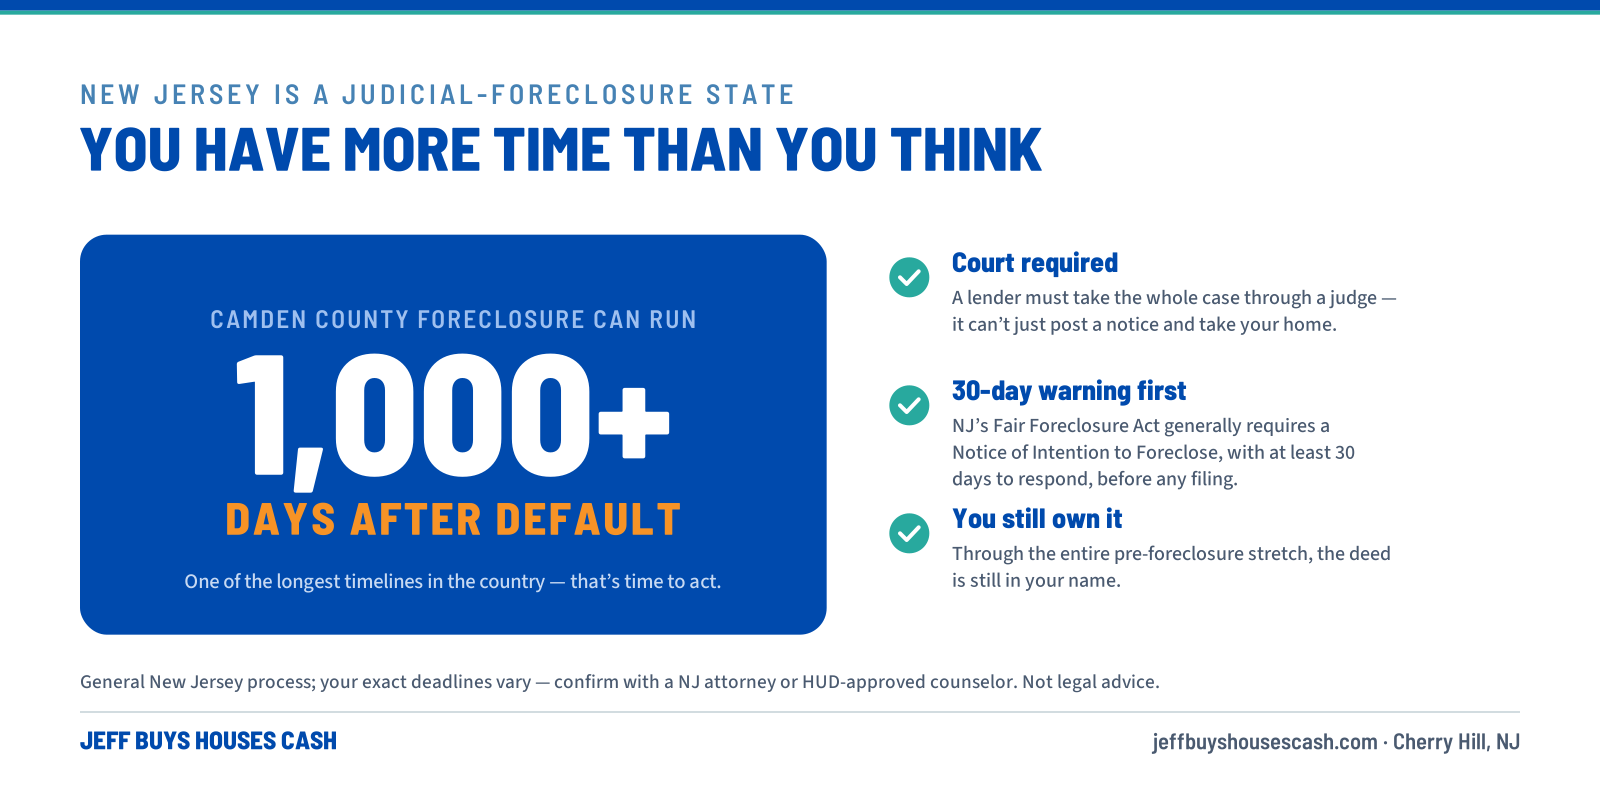
New Jersey is a judicial-foreclosure state. That means a lender can't just post a notice and take your house — it has to take the whole thing through court, in front of a judge. That process is slow on purpose. New Jersey has one of the longest foreclosure timelines in the country, and here in Camden County it can run well over 1,000 days from the time a loan goes into default. That's a hard way to live, I won't pretend otherwise — but it also means you are almost never as out of time as that first letter makes it feel.
Before a lender can even start, New Jersey's Fair Foreclosure Act generally requires it to send you a Notice of Intention to Foreclose and wait at least 30 days. That notice has to spell out what you owe and how to cure it. So the "pre-foreclosure" phase typically begins well before anyone files a single court paper — which is exactly why it's the best time to act. Once the lender does file and the case moves through the court toward a judgment and a scheduled sheriff's sale, your list of options gets shorter.
I'm giving you the shape of it, not legal advice — the exact deadlines and paperwork in your situation are things a NJ foreclosure attorney or a HUD-approved counselor should confirm. But the big picture holds: in New Jersey, pre-foreclosure usually comes with time to breathe and think.
Why pre-foreclosure is (believe it or not) good news
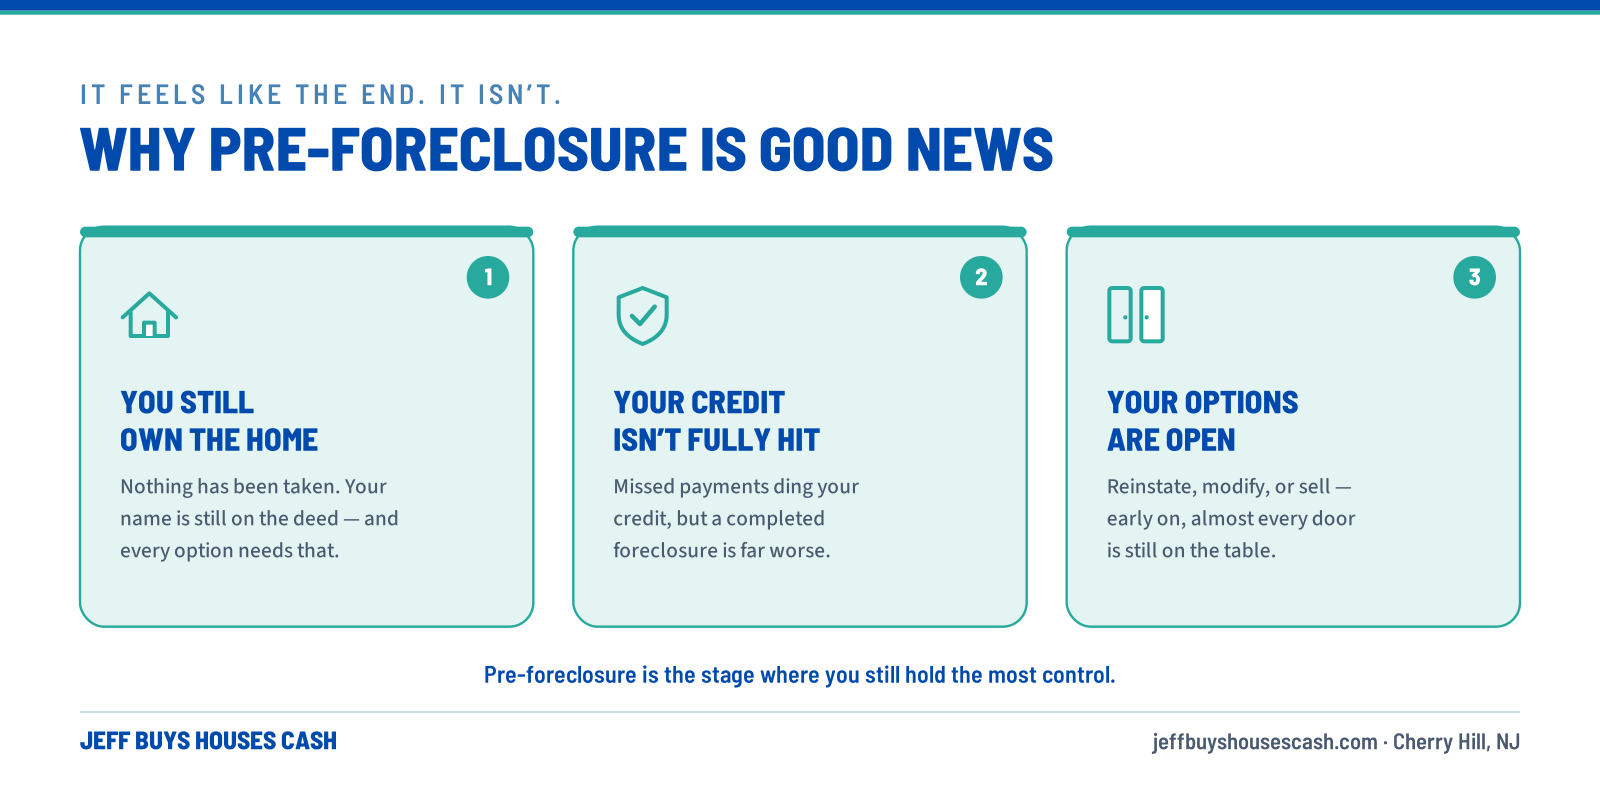
Three reasons this stage is the one you want to be in, not the one to hide from:
You still own the home. Nothing has been taken. Every option on the table requires that you still hold the deed — and right now, you do.
Your credit hasn't taken the full hit yet. Missed payments do ding your credit, there's no sugarcoating that. But a completed foreclosure is one of the heaviest marks you can carry, and it can follow you for years when you go to rent or buy again. Resolving things during pre-foreclosure — including selling before it finalizes — generally avoids that worst-case mark.
Almost every option is still available. Early on, you can reinstate, modify, or sell. Late in the game, after a judgment and a scheduled sale date, some of those doors have closed. Time is the one asset you can't get back here, so the earlier you move, the more you keep.
Your options during pre-foreclosure
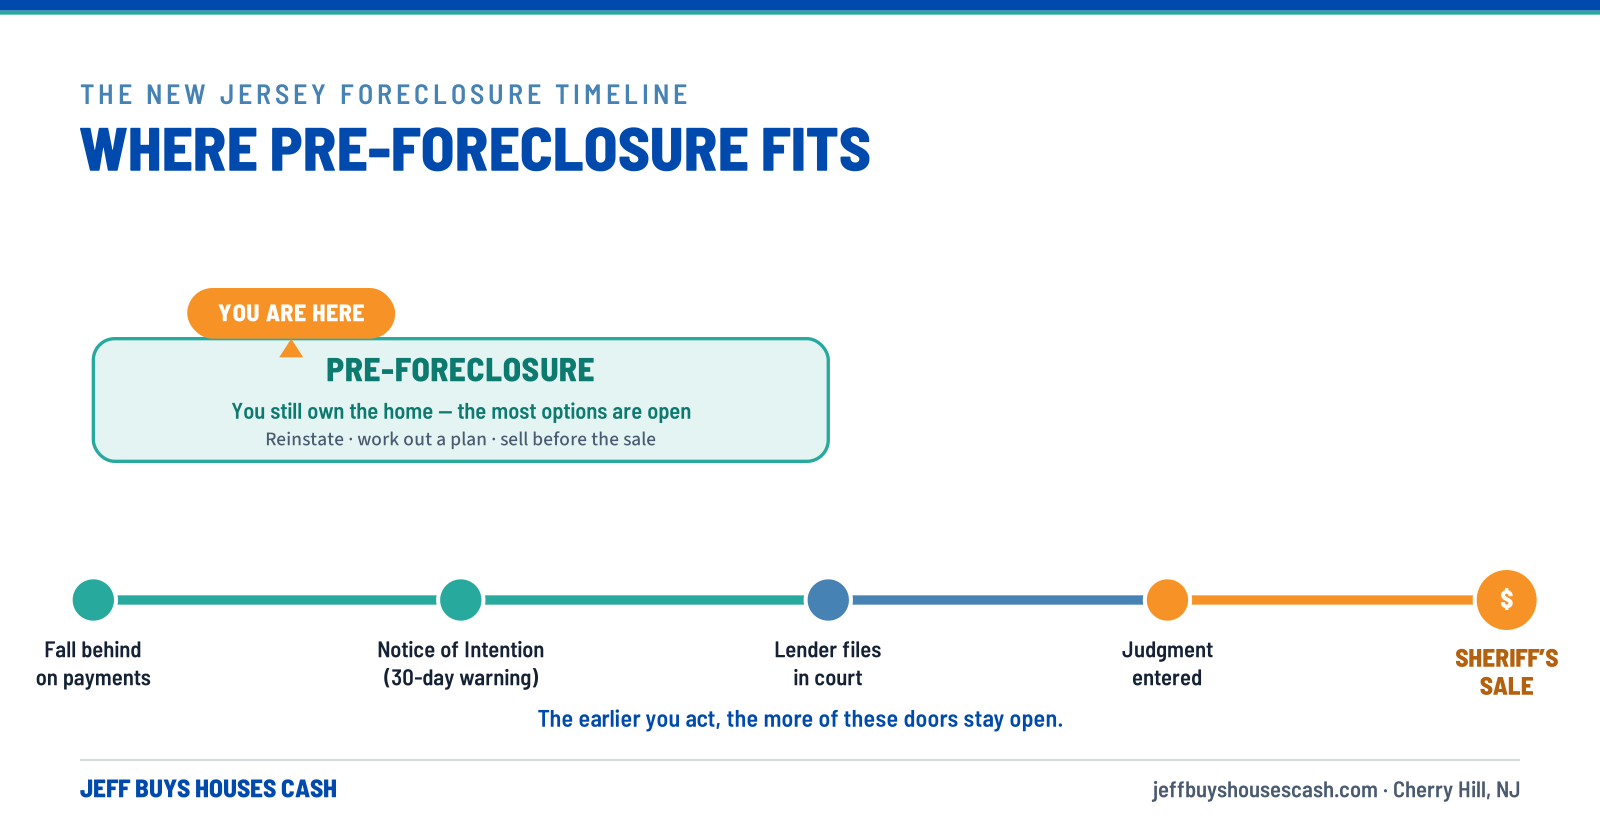
Depending on your situation, these are the paths homeowners in New Jersey actually take:
Reinstate the loan. If you can pay the past-due amount plus fees before the sale, you generally have the right to bring the loan current and stop the process. A HUD counselor or attorney can tell you your exact number and deadline.
Work out a plan with your lender. A loan modification, repayment plan, or temporary forbearance can make the payments workable again. Lenders often prefer this — foreclosing is expensive for them, too.
Sell before the sheriff's sale. You can sell right up until that sale. A fast cash sale can pay off what you owe, stop the foreclosure, and — if you have equity — put money back in your pocket instead of losing it at auction.
Explore terms or creative financing. Sometimes a structured deal solves a problem a straight sale can't, especially if you're close to the line on what's owed.
Get free, expert help. The NJ Department of Banking and Insurance offers foreclosure resources, and HUD-approved housing counselors will walk through your options at no cost. For the legal side, talk to a NJ foreclosure attorney. Please don't navigate that part alone.
For the full rundown of how to stop a foreclosure in NJ once you've got your footing, here's my pillar guide: How to Stop Foreclosure in Cherry Hill, NJ.
Where I fit in — before the sale date
Two honest ways I can help, depending on what you need:
Want to keep your options open? With 40-plus years at this, I can talk with your lender and, in situations that qualify, use creative financing to help you avoid foreclosure altogether.
Want a clean exit instead? I'll make a fair, no-obligation cash offer and buy the house as-is — no repairs, no cleanout, no fees — and close on your timeline, in as little as 7 to 10 days. Selling during pre-foreclosure can stop the process and let you close this chapter with cash in hand instead of a foreclosure on your record. (Here's how I buy houses, and what a fast cash sale in Cherry Hill actually looks like.)
Either way, I'll tell you straight whether selling is really your best move. Sometimes it isn't, and I'll say so — I don't try to make a deal, I try to help people.
This article is general information, not legal, financial, or tax advice. Your situation is specific to you — please confirm the details with a qualified New Jersey attorney or a HUD-approved housing counselor before making decisions.
Frequently asked questions
What does "pre-foreclosure" mean in New Jersey? It's the period after you've fallen behind on your mortgage but before the lender completes a foreclosure at a sheriff's sale. You still own the home and still have options to cure the default, work out a plan, or sell.
How long does pre-foreclosure last in NJ? It varies, but New Jersey is a judicial-foreclosure state with one of the longest timelines in the country — in Camden County the full process can run well over 1,000 days after default. That generally leaves meaningful time to act during the pre-foreclosure stage.
Can I sell my house during pre-foreclosure? Yes. You can sell right up until the sheriff's sale. A cash sale can pay off the loan and stop the foreclosure, and if you have equity it can put money back in your pocket instead of losing it at auction.
Will pre-foreclosure ruin my credit? Missed payments do affect your credit, but a completed foreclosure is far more damaging and can follow you for years. Resolving the situation during pre-foreclosure — including selling before it finalizes — generally avoids that worst outcome. For credit-specific guidance, talk to a HUD-approved counselor.
Does it cost anything to talk to Jeff about my options? No. The conversation and any cash offer are free, with no obligation. Jeff will tell you honestly whether selling is your best move — even if the answer is to list with an agent instead.
Don't wait for the letter to turn into a lawsuit
Pre-foreclosure is the stage where you still hold the cards. The worst thing you can do is nothing — the best thing is to understand your options while all of them are still on the table. I'll personally review your situation, lay out your real choices, and, if selling is the right move, make a fair, no-obligation cash offer. No pressure. No judgment.
Call or text me, Jeff, at (856) 281-1157, see all your options on my Stop Foreclosure page, or get a no-obligation cash offer.